Portugal's Quarterly Social Security Declaration for Freelancers
The declaration reports the previous three months and sets the base for the declaration month and following two months; each contribution is normally paid the next month.
- Submit in Segurança Social Direta by the last day of January, April, July, and October, reporting the immediately preceding three months.
- Relevant income is generally 70% of service revenue and 20% of sales of goods or hotel/restaurant revenue, subject to the statutory exceptions.
- The portal calculates a monthly contribution base from the quarter; the standard self-employed contribution rate is generally 21.4%.
- You can adjust the declared relevant income within the portal's permitted range, in 5% steps, before confirming.
- Since June 2026, SSD provides a downloadable proof of the submitted quarterly declaration.
Looking for proof of your Social Security debt status rather than reporting quarterly income? You need the contribution-status certificate. These are different documents.
Portugal's quarterly declaration tells Segurança Social what an eligible self-employed worker earned in the previous three months. Under Article 163 of the contributory code, the resulting base applies in the declaration month and the following two months; each monthly contribution is normally paid between the 10th and 20th of the next month. Filing it is separate from issuing recibos verdes or filing your annual IRS return, although the records should reconcile.
The four declaration windows
| Submit by | Revenue reported | Contribution months | Normal payment months |
|---|---|---|---|
| Last day of January | October–December | January–March | February–April |
| Last day of April | January–March | April–June | May–July |
| Last day of July | April–June | July–September | August–October |
| Last day of October | July–September | October–December | November–January |
Check the SSD deadline notice for the specific year when the last day falls on a weekend or holiday. The current official guide says declared elements can be replaced up to the 15th day after the deadline. A missing declaration can be submitted from the day after the declaration period until the end of the month before the next declaration period; late filing can still lead to recalculation or an administrative-offence process.
Which revenue becomes relevant income
The contribution is not calculated on every euro of turnover. Under the general quarterly regime, relevant income is ordinarily 70% of revenue from services and 20% of revenue from the production and sale of goods or from hotel and similar activities, catering, and drinks. The resulting quarterly relevant income is divided to establish a monthly base. Special categories and workers under organised accounting can follow different calculations.
| Revenue type | General relevant-income percentage |
|---|---|
| Provision of services | 70% |
| Production and sale of goods | 20% |
| Hotel/similar activity, catering and drinks | 20% |
Rate, base, and the adjustment option
For a self-employed worker in the standard regime, the contribution rate is generally 21.4% of the monthly contribution base. Individual entrepreneurs and certain establishment holders can have a different rate. During the declaration, SSD lets the worker choose an increase or reduction to the calculated relevant income in 5% steps, within the allowed 25% range. A lower base can reduce both the bill and benefit protection; do not treat the slider as a tax discount without considering that trade-off.
Declaration and payment are two separate actions
Submitting the quarter does not pay the monthly contribution. Contributions are normally paid between the 10th and 20th of the following month, using the payment reference shown in SSD or an active direct debit. Check the account every month after a declaration: a correction, exemption ending, or reassessment can change the amount. If no payment appears when you expect one—or a value looks inconsistent with the confirmed base—resolve it before the payment window closes. Keep the payment receipt beside the quarterly proof; together they show what was declared and what was actually paid.
Who may not have a quarterly declaration
Not every person with open activity files every quarter. Examples can include someone still in the initial contribution exemption, a worker whose exemption for simultaneous employment applies, a pensioner with a qualifying exemption, or a worker assessed under organised accounting rather than the quarterly regime. Exemptions have conditions and can change when employment income, employer relationship, or revenue changes, so confirm the status shown in SSD rather than assuming it continues.
How to reconcile before submitting
- Compare SSD's three monthly figures with the invoices and invoice-receipts issued in Portal das Finanças.
- Separate services from sales of goods because their relevant-income percentages differ.
- Check cancellations and credit notes rather than reporting only bank cash received.
- Use the amounts and classifications requested by SSD and reconcile each source month to the tax documents issued for that activity.
- Keep the submitted declaration, proof, and monthly payment documents together for the quarter.
New in 2026: download the declaration proof
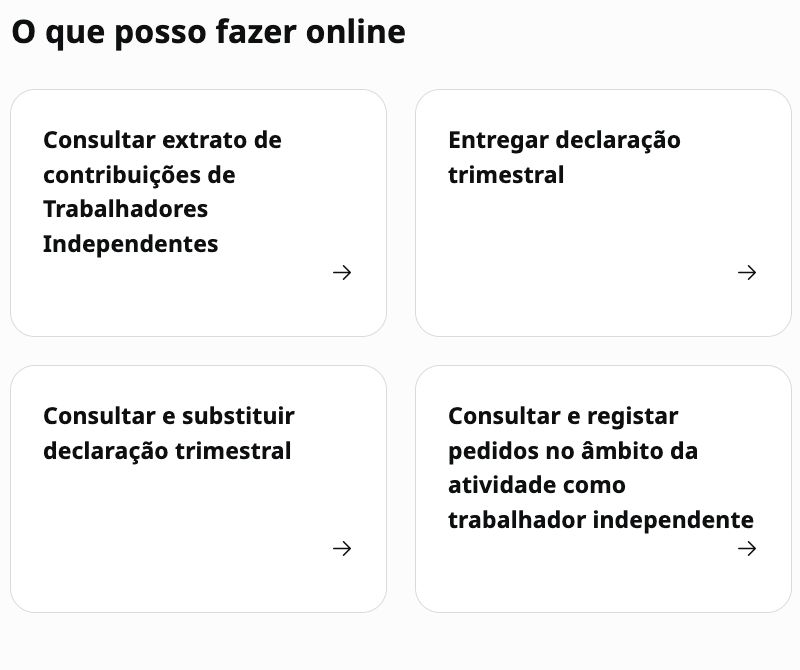
Segurança Social announced on 22 June 2026 that a proof of quarterly declaration can be downloaded in SSD. The path is Work (Trabalho) > Remunerations and contributions > Self-employed workers (Trabalhadores Independentes) > Consultar e substituir declaração trimestral. This is useful for loan, immigration, and compliance files and gives you a stable record of what was submitted rather than relying on a screenshot.
If you file late, or pay late
Two different windows exist, so check which one you need. A declaration you have not submitted can still be submitted from the day after the declaration period until the end of the month before the next one, according to the current official guide. A declaration you already submitted can be replaced up to the 15th day after the deadline. Both are done in Segurança Social Direta, and the replacement route is not the late-filing route.
Payment has its own rules in the Código dos Regimes Contributivos. The monthly contribution is due between the 10th and 20th of the following month (art. 155.º n.º 2), and paying late is an administrative offence: a light one if you comply within 30 days after the deadline and a serious one otherwise (n.º 4). Each year Segurança Social also reviews your declarations against the income the tax authority reports and notifies the difference, and what you pay as a result of that review is treated as paid late (art. 164.º-A). Whatever the result, check your account in SSD after any correction to confirm the recalculated contribution.
Enter the quarter's invoicing in the Social Security calculator to see the monthly base and contribution before the payments fall due.
Work out my monthly contributionFrequently asked questions
When is the quarterly declaration due?
By the last day of January, April, July, and October, for revenue in the immediately preceding three months. Check SSD's current notice when the date falls on a non-working day.
How long do I have to replace a declaration?
The current official guide says the declared elements can be replaced up to the 15th day after the filing deadline. Correct promptly in SSD and retain the replacement proof.
Can I change a declaration after submitting?
SSD provides a 'consult or replace quarterly declaration' route. The current guide gives until the 15th day after the deadline to replace declared elements; keep the new proof because the change can recalculate contributions.
Where can I get proof that I submitted?
Since June 2026, download it in SSD under Work (Trabalho) > Remunerations and contributions > Self-employed workers (Trabalhadores Independentes) > Consultar e substituir declaração trimestral.
Get the free Portugal tax playbook
A first-year PDF: NIF and NISS, NHR vs IFICI vs IRS Jovem, the Modelo 3 annex map and the deadline calendar. Sent to your inbox.