Rental Income Tax in Portugal: How Categoria F Works
For rent received in 2026, a new temporary 10% rule can replace the normal 25% housing rate. The rent ceiling and long-contract conditions matter, while short lets remain a different tax category.
- Qualifying housing rent no higher than €2,300 per month is taxed autonomously at 10% for income received from 1 January 2026 through 31 December 2029, unless a lower rate applies.
- You can deduct maintenance, condo fees, IMI, stamp duty, and rent-guarantee insurance actually paid — not mortgage interest, depreciation, furniture, or the property's purchase price.
- Outside the moderate-rent rule, housing rent starts at 25%. Eligible permanent-housing contracts can reduce that rate, but duration alone does not prove eligibility; a confirmed 20+ year contract can reach 5%.
- Alojamento Local income remains Category B. Moradia/apartamento operators can elect annually to use Category F taxation rules; this does not automatically qualify tourist accommodation for residential-lease relief.
Categoria F is the IRS category for rendimentos prediais — rent from urban, rural, or mixed-use properties paid or made available to the owner. It covers more than the obvious monthly rent: it also reaches money for letting out installed machinery or furniture, the margin a sublandlord keeps between what they charge and what they pay the owner, letting out common areas of a building for things like advertising, and compensation paid for lost rental income. If the property is genuinely part of a business or professional activity you run, you can opt to have that rental income taxed under Categoria B instead — otherwise it defaults to Categoria F.
What is the rental income tax rate in Portugal in 2026?
For income received in 2026, qualifying exclusively residential leases with monthly rent within the moderate-rent ceiling can use the temporary 10% rate in EBF Article 45-C, unless a lower rate applies. The 2026 ceiling is €2,300 a month: 2.5 times the 2026 national minimum wage of €920. Outside this relief, the ordinary residential rate is 25%; other Category F property income normally uses 28%. Resident aggregation and qualifying long-lease reductions are separate choices or rules, not a blanket 28% rental tax.
Is rental income tax charged on gross rent or after expenses?
Category F normally taxes rent after eligible, paid and documented expenses under Article 41. For example, €12,000 rent minus €2,000 eligible costs gives €10,000 net income; if the 10% housing rule applies, the autonomous tax is €1,000 before any separate tax credits. This example assumes the whole income qualifies and does not choose aggregation. Mortgage interest, furniture, appliances, depreciation and AIMI are not deductions from Category F rent.
Selling the property: capital gains and reinvestment.
AIMI: allowance, bands and the separate IRS credit.
The 10% moderate-rent rate is not the RSAA exemption
Distinction checked on 15 October 2026: the €2,300 moderate-rent ceiling (DL 97/2026 art. 2(2)(a), used by EBF Article 45-C) is not the RSAA ceiling. Portaria 454/2026/1, published on 13 October sets municipality/property-type limits for that separate scheme. Article 7 brings the Portaria into force the day after publication; repeal and transitional rules have their own effects. Moderate rent and tax-exempt affordable rent are not interchangeable.
| Route | What to establish |
|---|---|
| Moderate rent — 10% | Exclusively housing use, total property-rent ceiling and 2026–2029 window; a more favourable rate prevails. |
| Duration reduction | Permanent housing, term and the other Article 72 conditions; selecting a long contract is not enough. |
| RSAA — possible exemption | Municipality/type ceiling, purpose, term and IHRU communication; being below €2,300 does not establish eligibility. |
How to check RSAA and communicate the contract
- Find the right ceiling
Open IHRU's official service and choose Município and Tipologia. Check the Portaria's annex and the conditions for any uplift. Do not substitute the moderate-rent €2,300 ceiling.
- Check purpose and term
RSAA provides a three-year minimum for permanent residence and a three-month minimum for the temporary route, which has its own conditions. For rooms or temporary residence also read Annex III Article 3; do not automatically apply whole-home rules.
- Prepare both documents
Keep the contract copy and proof of registration with Finanças. AT registration does not replace the separate IHRU communication.
- Communicate and retain proof
Article 6 requires both documents to be submitted through IHRU's platform by 15 January following the contract year. Save the confirmation and check the contract details. A rent-limit calculation is not exemption approval; existing old-PAA contracts have a separate transitional rule.
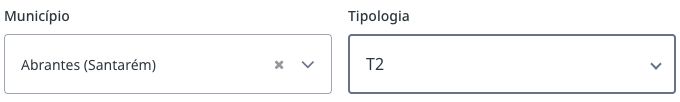
Check the authority: on 15 October the official simulator labelled one energy option B or higher, whereas Portaria Article 2(4)(b) requires A or higher for that uplift. Do not claim it solely on that interface label; confirm with IHRU. The illustrative lookup used no uplifts.
The tax rate: a flat rate, separate from your other income
For the contract-registration step, use our separate guide to registering a rental contract with Finanças. This page focuses on the income tax calculation.
Net rental income is normally taxed autonomously. CIRS Article 72(2) sets the base housing-rent rate at 25%, while other property income covered by Article 72(1)(e) remains at 28%. From 1 January 2026, EBF Article 45-C overlays a temporary 10% rate for qualifying housing rent within the moderate-rent ceiling. The housing provisions are not restricted to resident landlords. Resident taxpayers can opt to aggregate eligible rental income with other taxable income; non-residents should not use that resident comparison.
The 2026 moderate-rent rule: 10% up to €2,300 a month
Decree-Law 97/2026 defines the current ceiling as 2.5 times the minimum monthly wage provided for 2026. Decree-Law 139/2025 fixed that wage at €920, making the ceiling €2,300 as checked on 31 August 2026. EBF Article 45-C applies the 10% autonomous rate to income from contracts used exclusively for housing and received through 31 December 2029, unless another regime gives a lower rate.
The ceiling uses the total value for the property. Add amounts for permanently attached furniture, equipment or accessories and services that enhance the property, even if documented in separate legal arrangements. Multiple tenants do not split the ceiling. For a lease covering only part of a year, the decree measures monthly rent as the annual value divided by the months elapsed in that year.
What you can (and can't) deduct
- Deductible: any expense genuinely incurred and paid to obtain or maintain the rental income — maintenance and conservation work, mandatory condominium charges, IMI (municipal property tax) and stamp duty paid in that same tax year, and rent-guarantee insurance premiums.
- Conservation and maintenance costs paid up to 24 months before the lease even started still count, as long as the property wasn't put to any other use in the meantime.
- Not deductible: financial costs such as mortgage interest, depreciation, furniture, appliances, and comfort or decoration items, and the Adicional ao IMI (AIMI) — none of these reduce your taxable rental income.
- The property's purchase price itself isn't deducted from rental income at all — it only comes into play later, as the acquisition cost used to work out any capital gain when you eventually sell.
- If you sublet, the margin between the rent you charge and the rent you pay the owner gets no deduction of its own.
AIMI is not an expense, but it is not lost: art. 135.º-I CIMI lets you deduct it from the IRS tax, up to the part of the tax that is proportionate to your net rental income. How it works is in the AIMI guide.
Worked example: €1,200 monthly rent is not €1,200 tax
Assume 12 months of €1,200 housing rent in 2026 and €2,400 eligible, paid and documented annual costs. Assume the 10% rate applies, with no RSAA exemption, aggregation or separate tax credits. This is a Category F calculation, not an AT assessment.
| Step | Annual calculation |
|---|---|
| Gross rent | €1,200 × 12 = €14,400 |
| Eligible costs | €2,400 |
| Net taxable income | €14,400 − €2,400 = €12,000 |
| Autonomous IRS | €12,000 × 10% = €1,200 |
| Balance after those costs and IRS | €14,400 − €2,400 − €1,200 = €10,800 |
If a more favourable 5% duration rate is actually established, the same €12,000 base gives €600 autonomous tax; do not add 5% to 10%. At €2,500 monthly rent with neither an exemption nor confirmed relief, €30,000 − €2,400 = €27,600 at 25% gives €6,900. These are different scenarios, not eligibility promises. The balance excludes mortgage repayments and non-deductible spending.
In the calculator, rent is monthly and costs are annual. It multiplies rent by 12: if you received only six months or have rent arrears, its result is not your annual return. Do not turn €1,200 into €600 to simulate six months: that also changes the monthly-ceiling test. Reconcile the year's amounts paid or made available to you and their supporting records separately.
Lower rates for longer habitational leases
| 2026 housing-rent situation | Autonomous rate |
|---|---|
| Total monthly rent no higher than €2,300 | 10% (unless a lower rate applies) |
| Above €2,300; no confirmed duration relief | 25% |
| Confirmed permanent-housing lease: 5 to under 10 years | 15% |
| Confirmed permanent-housing lease: 10 to under 20 years | 10% |
| Confirmed permanent-housing lease: 20 years or more | 5% |
The duration reductions apply only to permanent-housing leases. The 5–10-year tier can fall by another two percentage points on each renewal of equal duration, capped at ten renewal points. For contracts signed from 2024, Article 72(23) blocks the reductions where monthly rent exceeds the applicable municipal and property-type benchmark by more than 50%. Early termination for a reason attributable to the landlord can claw the benefit back from the contract or renewal start, with compensatory interest. That is why the calculator never grants a duration reduction from the term alone.
The rental income estimator applies the 2026 moderate-rent rule, or a long-lease reduction you confirm, and shows the Categoria F tax on your rent.
Estimate my rental income taxShort lets: Alojamento Local isn't Categoria F
Alojamento Local (AL) is legally defined as an establishment providing temporary lodging services — to tourists, among others — for payment. Because that's a service, not a plain letting of the property, AL income falls under Categoria B (business and professional income), not Categoria F, from the moment you register the activity.
Under the regime simplificado, moradia/apartamento AL normally uses a 0.35 coefficient on gross receipts, or 0.50 in a designated área de contenção, followed by progressive IRS taxation. Article 28(14), however, permits an annual election to use Category F taxation rules for these AL modalities. AT FAQ 3306 confirms that the income itself remains Category B. Compare both treatments; tourist accommodation does not automatically become a residential lease eligible for EBF Article 45-C's temporary 10% rate.
Frequently asked questions
What is the rental income tax rate in Portugal in 2026?
For income received in 2026, qualifying exclusively residential leases with monthly rent within the moderate-rent ceiling can use the temporary 10% rate in EBF Article 45-C, unless a lower rate applies. The 2026 ceiling is €2,300 a month: 2.5 times the 2026 national minimum wage of €920. Outside this relief, the ordinary residential rate is 25%; other Category F property income normally uses 28%. Resident aggregation and qualifying long-lease reductions are separate choices or rules, not a blanket 28% rental tax.
Is rental income tax charged on gross rent or after expenses?
Category F normally taxes rent after eligible, paid and documented expenses under Article 41. For example, €12,000 rent minus €2,000 eligible costs gives €10,000 net income; if the 10% housing rule applies, the autonomous tax is €1,000 before any separate tax credits. This example assumes the whole income qualifies and does not choose aggregation. Mortgage interest, furniture, appliances, depreciation and AIMI are not deductions from Category F rent.
Which landlord expenses can I deduct from rent?
Keep documents for eligible maintenance and conservation, mandatory condominium charges and rent insurance. IMI and stamp duty are deductible when they concern a property whose income is taxed in that year. Qualifying maintenance paid in the 24 months before letting may count if the property had no other use meanwhile. Acquisition-loan interest and AIMI do not reduce net rent; a possible AIMI credit against IRS is a different mechanism.
Do non-resident landlords pay tax on Portuguese rent?
Portuguese-property rental income is not exempt merely because its owner lives abroad. Determine whether the residential 10% relief or a qualifying lower rate applies; otherwise the ordinary residential rate is 25%, while other Category F income normally uses 28%. Do not treat a non-resident's foreign tax return as a substitute for the Portuguese obligation, or assume the resident option for aggregation automatically applies to every non-resident.
Does a five-year housing lease automatically qualify for a lower rate?
No. Article 72's duration reductions concern permanent-housing leases and have additional conditions. The ordinary rates for qualifying terms of 5–under 10, 10–under 20 and at least 20 years are 15%, 10% and 5%, respectively; the temporary 10% moderate-rent rule can be more favourable. For new contracts from 2024, excessive rent relative to the municipal/property-type benchmark blocks duration relief. Qualifying renewals and a new rent at least 5% below the previous contract can produce further reductions. Early termination attributable to the landlord can trigger repayment with interest.
Can I deduct rent I pay after moving more than 100 km away?
Article 41(8) allows this within a specific Category F rule, up to the gross rental income: the property now let must have been your own permanent home and tax domicile for at least 12 months; your permanent residence must move more than 100 km away; and both leases must be registered with AT. This is not a general deduction for a landlord's personal housing costs. Keep evidence of the old domicile, distance, contracts and rent paid.
Answer checked on
Can Alojamento Local choose Category F taxation?
Income from AL remains legally Category B. However, an operator of moradia- or apartamento-type AL can elect each year to have that income taxed using Category F rules under Article 28(14). AT FAQ 3306 expressly says the income category does not change. Compare that annual option with the business regime rather than assuming progressive taxation is compulsory in every case. The option does not by itself turn tourist accommodation into an exclusively residential lease qualifying for the temporary 10% housing relief.
Is the 10% rate the same as an RSAA exemption?
No. EBF Article 45-C's moderate-rent rate and DL 97/2026 Annex III's RSAA are distinct. RSAA has municipality/type ceilings, contract requirements and IHRU communication. Portaria 454/2026/1 published its limits on 13 October. Being below €2,300 does not prove exemption; Finkavo's calculator does not validate RSAA eligibility.
Is registering the contract with Finanças enough for RSAA?
It does not replace the IHRU communication. RSAA Article 6 requires the contract copy and proof of AT registration through IHRU's platform by 15 January following the contract year, alongside the other conditions. Retain proof. Existing old-PAA contracts have separate transitional rules; selecting a calculator option is not approval of a new exemption.
What tax rate applies to rental income in Portugal?
For income received in 2026, qualifying housing rent at no more than €2,300 a month is 10% under EBF Article 45-C, unless a lower rate applies. Otherwise housing rent is 25% under CIRS Article 72(2), before a confirmed duration reduction. Other property income under Article 72(1)(e) is 28%.
What counts toward the €2,300 monthly-rent ceiling?
Use the total amount for the property, including permanently attached furniture, equipment or accessories and relevant services, even if covered by separate arrangements. Do not divide the amount among several tenants. For a partial year, divide the annual value by the months elapsed.
Can I have my rental income taxed together with my salary instead?
Resident taxpayers can opt to aggregate eligible rental income and pay progressive rates instead. Non-residents have separate Article 72 rules and should not use the resident englobamento comparison.
What expenses can I deduct from my rental income?
Maintenance and conservation work, mandatory condominium charges, IMI and stamp duty paid that year, and rent-guarantee insurance — provided you actually paid them and can document it. Mortgage interest, depreciation, furniture and appliances, and the AIMI surcharge are excluded.
Does signing a longer lease reduce my tax rate?
Potentially. For permanent-housing leases, the 25% rate can fall to 15% for 5 to under 10 years, 10% for 10 to under 20 years, and 5% for 20 years or more. But contracts from 2024 face a rent-benchmark test, and landlord-caused early termination can claw back the relief. Contract length alone is not enough.
Is short-term letting through Alojamento Local taxed the same as a regular rental?
AL income remains Category B. The simplified regime normally applies a 0.35 coefficient (0.50 in designated contention areas) before progressive IRS taxation. Moradia/apartamento operators may instead elect annually for Category F taxation rules under Article 28(14); the category remains B and the election does not automatically confer the 10% residential-lease relief.
Get the free Portugal tax playbook
A first-year PDF: NIF and NISS, NHR vs IFICI vs IRS Jovem, the Modelo 3 annex map and the deadline calendar. Sent to your inbox.