Registering a Lease at Portal das Finanças (Modelo 2)
The lease is not registered when you sign it. A landlord has until the end of the month after the tenancy starts to tell AT it exists — and the stamp duty falls due on the same day.
- The deadline is the end of the month AFTER the lease begins. A tenancy starting 12 March is due by 30 April. Count the month after the start, not thirty days from it.
- The stamp duty is 10% of one month's rent, one time, and since April 2015 the landlord pays it. It is not withheld from the tenant.
- The purpose box and the end date are not admin. They are what decides whether your rental income is taxed at 28%, 25%, 15%, 10% or 5%.
- If the landlord does not communicate it, the tenant may. Article 60.º n.º 4 says so explicitly.
- Six common situations cannot be done on the portal at all and go through e-balcão instead — including a landlord change after you buy a tenanted flat.
In Portugal a lease is a fact the tax authority has to be told about, separately from signing it. The duty sits on the landlord, it is in article 60.º of the Código do Imposto do Selo, and the instrument is a declaration called the Modelo 2. Registering also triggers a one-off stamp duty on the rent, and it is what makes the electronic rent receipts possible afterwards.
Nothing here is optional for a landlord letting a flat, a shop, a parking space, a room, or the roof of a building to a phone company. If money is being paid for the use of a property, article 60.º applies.
Who has to communicate it, and by when
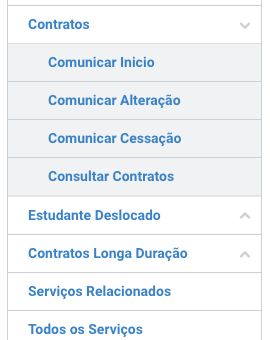
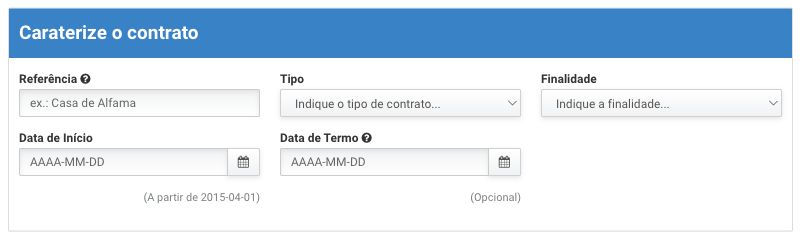
Article 60.º n.º 1 puts the obligation on the locadores and sublocadores — landlords and sublandlords — and it covers four events, not one: the start of a lease or sublease, an alteration to it, its termination, and a promissory lease once the property has been handed over.
Article 60.º n.º 2 sets the deadline: the end of the month FOLLOWING the month of that event. This is not thirty days, and reading it as thirty days is the commonest way to be late. A tenancy that begins on 2 March and one that begins on 30 March share the same deadline: 30 April.
| Lease starts | Communication and stamp duty due by |
|---|---|
| 2 January | 28 February |
| 30 March | 30 April |
| 1 August | 30 September |
| 31 December | 31 January of the following year |
If the landlord does not do it, article 60.º n.º 4 lets the tenant or subtenant do it instead, in the same official form. That is a real remedy, not a technicality: a tenant who needs the contract on record to claim the rent deduction in their own IRS is not left waiting on a landlord who will not file.
What it costs, and who pays
Verba 2 of the Tabela Geral do Imposto do Selo charges 10% on the rent corresponding to ONE month — not on the whole contract. For a lease shorter than a month with no possibility of renewal, the 10% falls on the rent for that period instead. The same 10% applies again to any agreed rent increase, on the increase alone.
- A lease at 800 € a month, of any length: 80 €, once.
- The same lease later raised by agreement to 900 €: a further 10 € — 10% of the 100 € increase — and an alteration to communicate.
- A one-week holiday let at 250 €: 25 €.
The landlord pays it. Article 41.º of the Código do Imposto do Selo says the verba 2 tax is paid by the locador or sublocador, and article 3.º n.º 3 b) puts the economic burden there too. That has been the position since 1 April 2015, when Lei 82-B/2014 took effect. Anyone still deducting the stamp duty from the tenant's first rent is applying a rule that stopped being law more than ten years ago.
Article 44.º n.º 6 ties the payment deadline to the communication deadline, so both fall on the same day. AT assesses the tax when you submit and hands back a documento único de cobrança; there is nothing to calculate yourself.
There is one exemption worth knowing. Article 7.º n.º 1 y), added by Lei 56/2023, exempts leases under the Programa de Apoio ao Arrendamento (Decreto-Lei 68/2019) — since 1 September 2026 read as leases under its successor, the RSAA (Decreto-Lei 97/2026, art. 14.º a); programme leases already in force keep their tax treatment, art. 15.º n.º 2) — and contracts made under public housing programmes run by the Autonomous Regions. Rural leases are exempt too, but they follow a different route entirely — see below.
The two boxes that decide your tax rate
Most of the Modelo 2 is identification. Two fields are not, and they are worth more than the rest of the form put together, because AT reads your IRS rate off them.
Field 05, Finalidade, has four options. Choosing a housing purpose or not is what separates article 72.º n.º 2's 25%, which applies to every arrendamento habitacional, permanent or not, from article 72.º n.º 1 e)'s 28%. A shop, an office, a warehouse or a parking space is não habitacional and is taxed at 28% — and gets no duration reduction at all, because numbers 3 to 5 of article 72.º each say habitação permanente.
Fields 07 and 08, the end date and whether the contract renews, are how AT knows the duration. The reductions are in whole percentage points off the 25%: ten points for five to ten years, fifteen points for ten to twenty, twenty points for twenty or more. A contract of five to ten years earns a further two points for each renewal of equal length, capped at ten points of renewal. Leave field 07 blank on an open-ended contract and there is no duration for AT to read.
| Contract | Rate | Source |
|---|---|---|
| Non-housing, any length | 28% | CIRS art. 72.º n.º 1 e) |
| Non-permanent housing, any length | 25% | CIRS art. 72.º n.º 2 |
| Permanent housing, under 5 years | 25% | CIRS art. 72.º n.º 2 |
| Permanent housing, 5 to 10 years | 15% | art. 72.º n.º 3 (−10 points) |
| …each equal renewal | −2 points, to a floor of 5% | art. 72.º n.º 3 |
| Permanent housing, 10 to 20 years | 10% | art. 72.º n.º 4 (−15 points) |
| Permanent housing, 20 years or more | 5% | art. 72.º n.º 5 (−20 points) |
There is a temporary rate on top of this. EBF article 45.º-C, added by Decreto-Lei 97/2026, taxes rental income from contracts exclusively for housing at 10% where the monthly rent stays within the limits in article 2.º of that decree, for income received up to 31 December 2029 — but only "salvo quando seja aplicável uma taxa mais favorável". A twenty-year lease keeps its 5%. The 10% cannot make anyone worse off.
Field 29 is where that rent limit is read from, which is the second reason to get the rent right rather than approximately right.
Once the contract is registered, the rental income estimator gives you an estimate of the Categoria F tax on the rent.
Estimate the tax on my rentFilling the rest of the form
- Field 13, Artigo — the matriz number. A property not yet on the matriz needs the IMI Modelo 1 first; the provisional artigo carries a P prefix.
- Field 16, Parte arrendada — fill this in only when you are letting part of a property: a room, a floor of a house, an annexe, one office in a suite, part of a plot.
- Field 17, Parte comum — for a common part of a building in propriedade horizontal with no matriz entry of its own: the porter's flat, a parking bay in a shared garage, a roof let for an antenna.
- Field 22 and 23, marriage regime and spouse NIF — only when the let property is a bem comum do casal. In compropriedade or separação de bens these stay empty and both owners go in as separate landlords with their shares.
- Field 24, Quota-parte — a fraction, and the shares of all named landlords must sum to 1.
- Field 30, Despesas — condominium fees or an insurance premium that is legally yours but which the contract makes the tenant pay on top. An annual figure is divided by twelve.
- Fields 34 and 35 — if you want an accountant or agent to file for you, this is where the authorisation is granted. Article 9.º n.º 3 of the portaria is blunt about the consequence: non-compliance stays the taxpayer's, whoever was authorised.
What the portal will not let you do
The Modelo 2 online accepts as landlord only the owner recorded on the matriz. That single limitation, plus a handful of operational rules AT publishes in its own FAQ, produces a set of situations where the portal is a dead end and the route is e-balcão instead. Knowing this in advance saves an afternoon.
- You bought a flat that was already let and need the landlord changed on the existing contract.
- The tenant died and the contract must pass to the surviving spouse — a change of locatário.
- The landlord died and the contracts are in their name.
- You are the landlord under a comodato or a locação financeira (leasing), so you are not the owner on the matriz. Send the comodato or leasing contract along with the lease.
- The property's address on the matriz is wrong or out of date.
- There are several landlords and the one who filed cannot make the alteration or the termination — only the original declarant can do those on the portal.
Cases with their own route
- Undivided inheritance — the landlord is the herança indivisa itself, represented by the cabeça de casal. The inheritance needs its own NIF and its own portal password; the heirs are NOT named as landlords.
- Condominium letting a common part — the landlord is the condomínio. The administrator must first go to a serviço de finanças with the assembly minutes to have the authorisation registered, then file in the condominium's name.
- Rural leases (Decreto-Lei 294/2009) — not communicated on the portal at all. They go to the competent serviço de finanças within 30 days of signature, with the original contract, and they are exempt from stamp duty.
- Comodato — a loan-for-use is not subject to article 60.º at all. There is nothing to communicate.
- A rent updated by the statutory coefficient — communication is not required, because it is not an agreed increase. You can still communicate it if you want the receipts pre-filled with the new figure.
Contracts that started before April 2015
The communication obligation took effect on 1 April 2015. A contract that started earlier, and on which the stamp duty was paid at the time at the serviço de finanças, does not need registering again. But alterations and the eventual termination of that contract do have to be communicated through the portal — so AT recommends registering the old contract voluntarily, because that is what makes the electronic rent receipts work later.
After registration: rent receipts, or the Modelo 44
Registering the contract is what unlocks the recibo de renda eletrónico. Article 115.º n.º 5 of the CIRS gives Category F landlords a choice of two duties, not an option to do neither: either issue an official-model receipt for every amount received from the tenant, or file a declaration itemising that income by the END OF FEBRUARY each year for the year before.
That February date is worth pinning. It was January until Decreto-Lei 49/2025 changed article 115.º with effect from 1 July 2025. Portaria 98-A/2015 still says January in its own article 8.º and has not been updated — the Code prevails, and a great deal of published advice has not caught up.
You are exempt from issuing electronic receipts if you have no caixa postal eletrónica and are not obliged to have one AND your Category F income last year stayed under twice the IAS — 1 074,26 € for 2026. Both conditions, not either. Separately, and on their own, landlords who were 65 or older on 31 December of the previous year are exempt, as are rural leases. Anyone exempt may opt in, and from the first electronic receipt the general rules apply.
If you miss the deadline
A late or missing communication is a contra-ordenação under article 117.º n.º 1 of the RGIT, punishable by a fine of 150 € to 3 750 €. Article 26.º n.º 4 doubles both ends of that range for a company. The stamp duty is still owed on top, and article 27.º n.º 2 says the fine is graded by how long the omission ran — which is the practical argument for filing late rather than not filing.
Before closing the Portal: a completion checklist
- Check the submitted property, parties/shares, dates, purpose and rent against the agreement—not an example from a guide.
- Save the submission and collection document. Save proof of payment separately: issuing a payment document is not paying it.
- Treat contract registration, stamp duty and each rent receipt as separate tasks. Registration alone does not complete the annual IRS return.
- If you bought an already-let property, do not create a duplicate lease to work around the landlord field. FAQ 5028 directs the landlord change preferably to e-balcão.
Check AT's current lease FAQs, then continue with the rental-income guide and rental-income calculator. A calculation is not a payment reference.
One registration, three consequences
It is easy to read the Modelo 2 as paperwork with a small tax attached. It is better understood as the moment your rental income acquires a tax identity. The purpose box fixes your rate band. The dates fix your reduction. And article 41.º n.º 8 of the CIRS — the deduction for a landlord who lets their own home and moves more than 100 km away — requires in terms that BOTH leases be registered at Portal das Finanças. An unregistered contract is not a small administrative gap; it is a set of reliefs you cannot reach.
Frequently asked questions
I bought a property with an existing tenant. Should I register another lease?
Do not create a duplicate just to replace the landlord. AT FAQ 5028 says the landlord change following acquisition cannot be made directly in the lease area and should preferably be requested through e-balcão. Keep the existing contract and acquisition evidence.
Answer checked on
Must every annual rent update be communicated as a contract change?
No. FAQ 5005 distinguishes a statutory rent update, which can be reflected directly in the receipt, from an increase agreed by the parties. FAQ 5069 explains the contract-alteration route for an agreed change. Identify which situation applies before filing.
Answer checked on
Is the deadline thirty days?
No, and this is the commonest mistake. Article 60.º n.º 2 gives you until the end of the month following the month in which the lease started. A lease beginning on 30 March is due on 30 April, the same as one beginning on 2 March.
Who pays the stamp duty, the landlord or the tenant?
The landlord. Article 41.º of the Código do Imposto do Selo says the verba 2 tax is paid by the locador or sublocador, and article 3.º n.º 3 b) places the economic burden there. It stopped being the tenant's on 1 April 2015.
How much is it?
10% of one month's rent, once. For a lease shorter than a month with no renewal, 10% of the rent for that period. An agreed rent increase is charged the same 10% on the increase alone.
My landlord will not register the contract. Can I?
Yes. Article 60.º n.º 4 lets the tenant or subtenant file the official-model declaration when the landlord has not.
We are three co-owners. Do all of us have to file?
No. One of you files and names the others with their quota-parte, and that releases the rest. Whoever files becomes the taxable person for the stamp duty. Note that only the person who filed can later communicate an alteration or the termination on the portal.
I bought a flat that was already rented. How do I take over the contract?
Not on the portal. A change of landlord after buying a tenanted property has to be requested through e-balcão — the Modelo 2 online only accepts the owner recorded on the matriz for a new contract.
The rent went up by the annual statutory coefficient. Do I have to report it?
No. A statutory update is not an agreed increase, so communication is not required and no further stamp duty arises. You can report it anyway if you want the electronic receipts pre-filled with the new amount.
Do I have to use the internet?
In principle yes. You may file at any serviço de finanças if you have no caixa postal eletrónica and are not obliged to have one and your Category F income last year was under twice the IAS, or if you were 65 or older on 31 December of the previous year.
I registered a contract by mistake. Can I cancel it?
Yes, through Consultar contrato and then Anular — but not if receipts have already been issued against it. Cancel the receipts first.
Does a comodato have to be communicated?
No. A loan-for-use is not subject to the article 60.º obligation. But if you then let the property as a comodatário, you are not the owner on the matriz, so that lease has to go through e-balcão with both contracts attached.
Get the free Portugal tax playbook
A first-year PDF: NIF and NISS, NHR vs IFICI vs IRS Jovem, the Modelo 3 annex map and the deadline calendar. Sent to your inbox.